
What is casino game aggregation, exactly?
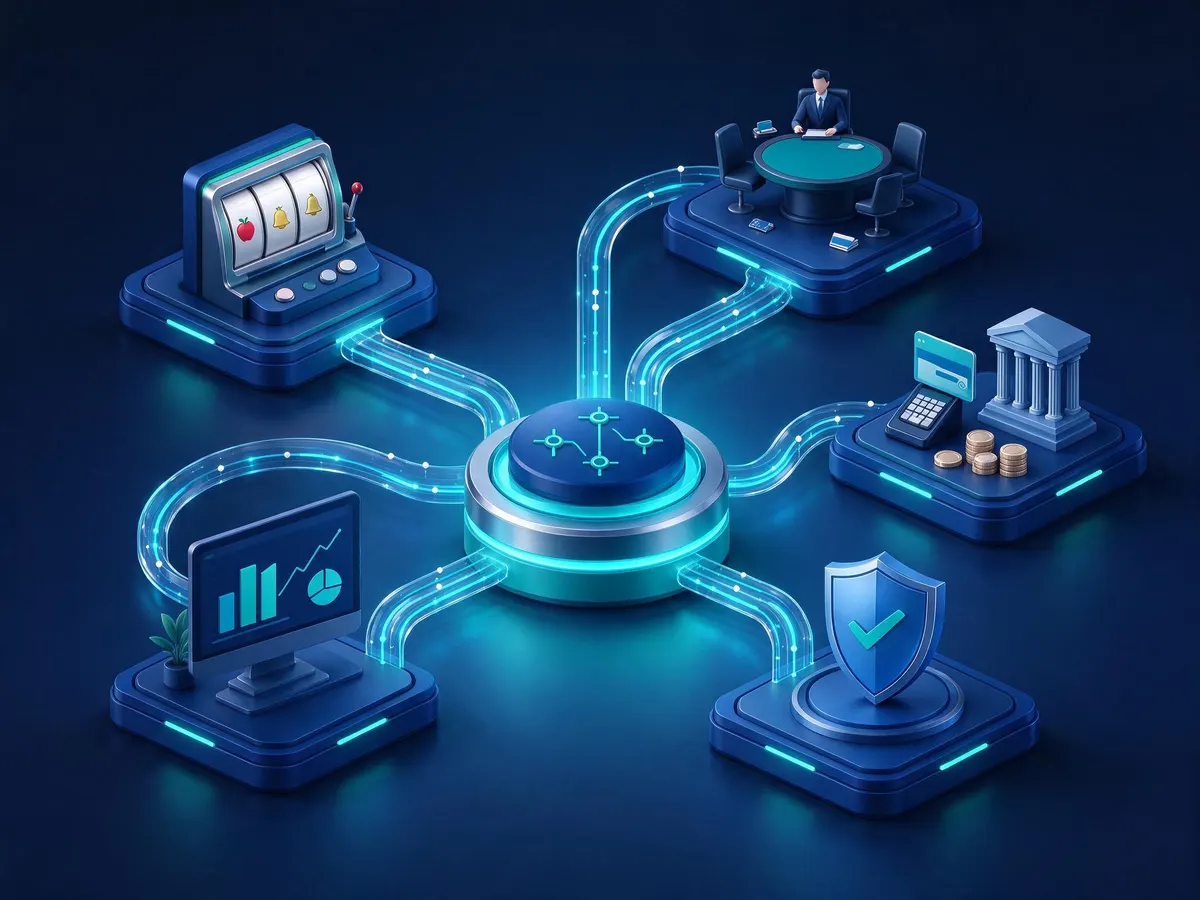
How many separate technical integrations should it take to launch an online casino? If your answer is “a few dozen”, you already understand why casino game aggregation exists. An aggregator is a middleware layer that connects you once, through a single API, to the catalogues of many game studios at the same time. You build to the aggregator’s specification; it handles the plumbing to each provider behind it.
Without that layer, every studio you want on your site is its own project: contracts, technical documentation, a sandbox environment, wallet integration, certification in each market, then ongoing maintenance whenever either side pushes an update. With a few providers that’s manageable. With a lobby of 5,000-plus titles from dozens of studios, it isn’t.
How do aggregation platforms work under the hood?
The mechanics are less mysterious than the marketing suggests. In broad terms:
- One integration, one wallet protocol. You expose your player wallet to the aggregator (or use a seamless-wallet style transfer model), and every game behind the aggregator debits and credits through that same set of endpoints.
- Game launch and session handling. Your front end requests a game URL with a token, currency, language and jurisdiction; the aggregator routes it to the right provider instance and returns a playable session.
- Bet and win transactions. Rounds are passed back as standardised transaction calls, so a spin on a Megaways slot and a hand of live Teen Patti arrive in the same format.
- Reporting and reconciliation. Gross gaming revenue, rounds, bonus spend and provider-level fees land in one reporting feed instead of thirty.
- Campaign tooling. Free-round and tournament mechanics are issued through the aggregator’s layer rather than configured studio by studio.
The real value is maintenance, not the first launch. When a studio changes its API version or releases a new title, the aggregator absorbs the work. Your dev team doesn’t.
What does the traditional game-only model cover?
The classic aggregation deal is content and nothing else: access to the catalogue, revenue share on GGR, a back office to switch games on and off per market, and some promotional tools. Payments, player accounts, bonusing engine, KYC, analytics, sportsbook and regulatory reporting all stayed with the operator or came from separate suppliers.
That worked when the number of regulated markets was small and the compliance load was lighter. It’s getting harder to defend now, and that’s the argument the industry has started making out loud.
Why are industry leaders pushing for broader aggregation than games?
The clearest recent statement of this came from Alexandre Tomic, founder of Alea, who put it bluntly: aggregation has to become broader than games. Speaking in connection with SBC Summit Lisbon, Tomic framed the game-only model as too narrow for what operators now have to manage. Alea is extending its own offering into payments, jackpots and sportsbook, having launched its sportsbook vertical with FIRST.bet and now pushing that solution out to operators. The company also plans to expand its jackpot product and has lined up appearances at SBC Summit Lisbon and SiGMA Rome.
His reasoning is grounded in how markets have changed rather than in product positioning. Brazil is a good illustration, and remains one of Alea’s priority markets despite higher taxes, steeper marketing costs and heavier compliance requirements than operators were used to. Tomic’s point there is that you cannot simply port a European playbook into Brazil: player behaviour and market trends move quickly, and what works in one regulated market doesn’t transfer cleanly to another.
Follow that logic and the conclusion is uncomfortable for a pure content supplier. If an operator’s hardest problems are local payment rails, tax and reporting obligations, acquisition economics and reacting fast to behaviour shifts, then handing them 10,000 games and walking away solves the easy part.
What services are content aggregation platforms now adding?
Expansion tends to follow the operator’s pain points in order. Here’s where the additions are concentrated.
Payment integration
Payments are the most obvious gap, because they’re the most local part of the business. A player in India expects UPI; one in Brazil expects Pix; elsewhere it’s cards, bank transfer or e-wallets. Each method means a provider contract, an integration, reconciliation logic and its own failure modes.
When an aggregator adds a payments layer, the pitch is the same as with games: one integration, many providers underneath, with routing between them. The practical gains are fewer failed deposits (because you can fail over to a second processor), faster withdrawal handling, and one reconciliation view that ties deposits, wagering and payouts together rather than splitting them across systems.
Data and analytics tools
Aggregators already sit on the transaction flow, which makes them a natural place to build reporting. Instead of a raw revenue feed, operators increasingly get an operator dashboard covering game-level performance, cohort retention, bonus cost against net revenue, and which titles actually convert new depositors versus which just fill the lobby.
That matters for the point Tomic makes about fast-moving markets. If player preferences in a market shift within weeks, monthly provider statements are too slow to act on. Multi-provider data in one place lets you reshuffle the lobby, adjust free-round campaigns and cut underperforming content while it still matters.
Compliance and regulatory support
This is the least glamorous piece and probably the most valuable. Regulated markets differ on which certified game builds are permitted, which mechanics are restricted, what must appear in-game, what reporting goes to the regulator, and which responsible gambling tools must be available. Multiply that by every market you hold a licence in.
Aggregators have started handling jurisdiction-level content filtering, certified build management and standardised reporting outputs so operators aren’t rebuilding the same logic per market. Player protection tooling, deposit and loss limits, cool-off and self-exclusion, sits better at platform level too, since a limit means little if it only applies to part of a player’s activity.
How does the model compare in practice?
The three approaches differ less in what they deliver and more in who carries the integration and compliance burden.
| Factor | Direct studio integrations | Game-only aggregator | Full-service aggregation |
|---|---|---|---|
| Integrations to build | One per provider | One for all games | One for games, payments and tools |
| Time to market | Slowest | Faster for content | Fastest for a full stack |
| Payments | Operator’s responsibility | Operator’s responsibility | Included or routed via the platform |
| Reporting | Fragmented per provider | Unified game reporting | Unified across games and payments |
| Market compliance work | Repeated per provider, per market | Partly handled | Largely handled at platform level |
| Dependency risk | Spread across suppliers | Concentrated in one vendor | Heavily concentrated |
| Commercial terms | Negotiated directly | Aggregator margin on GGR | Bundled, harder to unpick |
What does broader casino platform technology change for operators and players?
For you as an operator, the gain is bandwidth. Every integration you don’t own is engineering time redirected to acquisition, retention and local market work. Launching a new jurisdiction becomes a configuration exercise rather than a rebuild, which is what “time to market” actually means once the licence is in hand.
There’s a trade-off and you should price it in. Concentrating games, payments, jackpots and sportsbook with one vendor means a single point of failure, less room to negotiate individual provider terms, and a harder exit if the relationship sours. Ask how content is portable, what happens to your player data, and whether you can route payments to your own processors when you need to.
Players feel it indirectly. Deposits that go through first time, withdrawals that clear without a support ticket, a shared balance across casino and sportsbook, and jackpots that span multiple studios all come from the same consolidation. None of it changes the underlying maths of the games, RTP, volatility and the house edge are set by the studio and certified, not by the aggregator. Anyone playing should still set deposit and session limits and treat gambling as paid entertainment, not income.
Where are game integration providers heading next?
Two models are forming in parallel, and both will survive. One is the one-stop shop Tomic is building toward at Alea: games, payments, jackpots and sportsbook from a single supplier, aimed at operators who want speed and a thinner internal tech team. The other is the specialist, a studio or payment provider that goes deep on one thing and plugs into whichever platform the operator already runs.
The group under most pressure is the middle, pure content aggregators with no answer on payments, data or compliance. If the hardest parts of running a casino in Brazil are tax, marketing cost and regulatory load rather than catalogue size, the supplier who only solves catalogue size becomes a commodity.
If you’re evaluating platforms this year, judge them on the unglamorous items: payment success rates by market, how fast a new jurisdiction can be switched on, what the reporting actually shows you, and how much of your compliance obligation they genuinely carry. That’s where the broader definition of aggregation earns its keep.